

PMS for NRIs: Accounts, Tax and the 2026 Rule Changes
PMS for NRIs lets a non-resident Indian own a managed portfolio of Indian shares from ₹50 lakh. A SEBI-registered portfolio manager runs it, and the shares sit in the investor’s own demat account. The gains and the tax belong to the investor, as they would for a resident client.
The differences lie in the plumbing. The bank account behind the PMS decides how freely the money can go back abroad. Tax leaves the account with every profitable sale. And some countries of residence narrow the choice of manager.
This guide covers accounts, tax, repatriation, the GIFT City alternative and the 2026 rule changes. Information is as of 7 October 2026.
In this article11 sections
PMS for NRIs at a glance
| Point | Position |
|---|---|
| Who can invest | NRIs and OCIs, if the portfolio manager accepts non-resident clients |
| Minimum | ₹50 lakh in cash or securities (SEBI) |
| Accounts needed | NRE or NRO bank account, NRI demat account, NRI trading account |
| Repatriable route | Funded from abroad or a repatriable account; proceeds can go back abroad |
| Non-repatriable route | Funded from NRO; repatriation capped at USD 1 million a financial year |
| Tax on gains | Deducted at source on each sale: 20% short-term, 12.5% long-term, plus surcharge and cess |
| Fees | Fixed, performance-linked or both, plus 18% GST |
| Exit load | Up to 3% in year one, 2% in year two, 1% in year three, nil after |
| GIFT City option | IFSC portfolio manager, USD 75,000 minimum, in US dollars |
Information as of 7 October 2026. Sources: SEBI PMS FAQs (September 2024); RBI and FEMA notifications of June 2026; IFSCA (Fund Management) Regulations 2025.
A PMS account works like a personal fund. The manager buys and sells shares for the investor, and every holding shows up in the investor’s own demat account. The investor can exit at any time, subject to the exit load. The main risks are the manager’s stock choices, the rupee’s swings against the home currency, and tax on each profitable sale.
Who can open a PMS account from outside India
Non-resident Indians and overseas citizens of India can both invest. The investor needs three accounts in India. They are an NRE or NRO bank account, an NRI demat account and a trading account with the manager’s broker. KYC, a FATCA self-declaration and proof of overseas address complete the file.
Eligibility in law is wider than eligibility in practice. Each portfolio manager decides which countries of residence it accepts, and the list differs from one manager to the next. US and Canadian residents find the shortest lists, for reasons covered further down.
A June 2026 change to the FEMA rules opened this listed-share route to any individual resident outside India. That change covers listed shares. It does not by itself open every PMS to foreign nationals.
NRE or NRO: the account choice behind PMS for NRIs
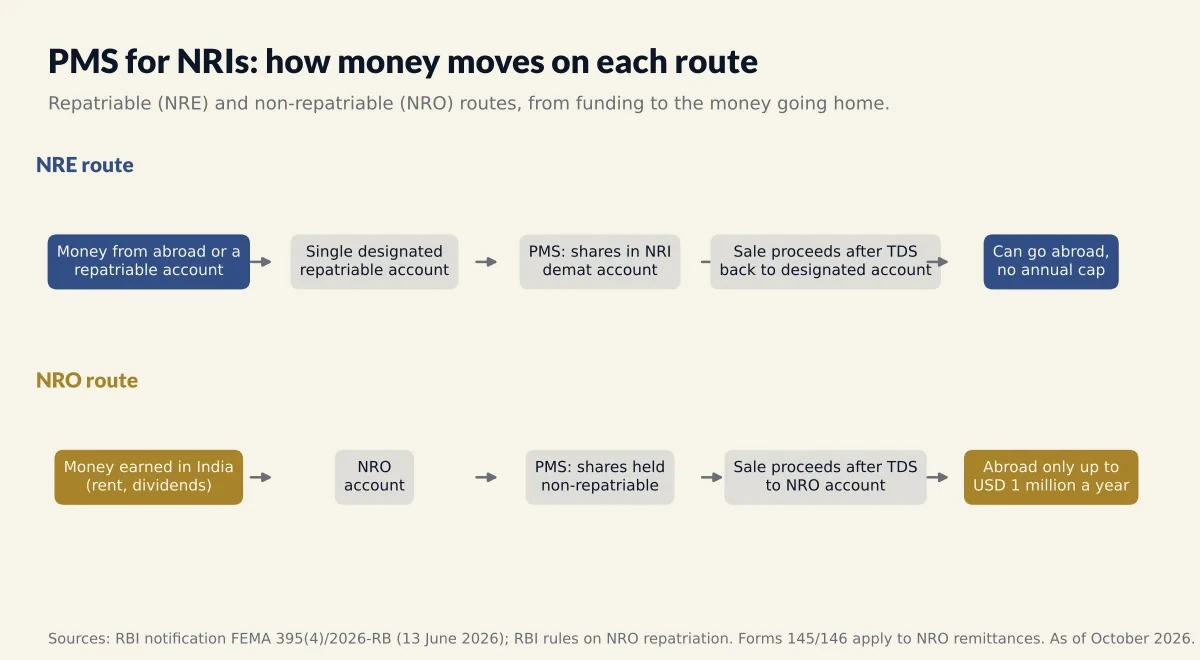
The NRE route suits money earned abroad. Funds come from overseas or from a repatriable account, and the investor holds the shares on a repatriation basis. Sale proceeds can then go back abroad with no annual cap.
The NRO route suits money earned in India, such as rent, dividends or the proceeds of an old property. The investor then holds the shares on a non-repatriation basis. Money can still leave NRO, but only up to USD 1 million per financial year. That limit also covers the sale proceeds of other assets.
The two routes stay separate. Repatriable investments run through one designated repatriable account that serves no other purpose. Non-repatriable ones run through NRO. The investor picks the source before the first rupee goes in.
What changed for NRIs investing through PMS in 2026
Four changes this year affect PMS for NRIs. Two are in force; two await notification.
| Date | Change | Status |
|---|---|---|
| 12 June 2026 | Individual holding in a listed company raised to below 10% of paid-up capital (was 5%); all such investors together capped at 24%. A breach must be sold down within 5 trading days of settlement | In force |
| 13 June 2026 | Purchases can be funded from any repatriable deposit account. Proceeds go to the investor’s single designated repatriable rupee account, through a designated bank. Reporting moved to Form LEC(IFI) | In force |
| 1 April 2026 | Remittance forms 15CA and 15CB replaced by Forms 145 and 146; treaty Form 10F replaced by Form 41 | In force |
| 24 September 2026 | SEBI Board approved treating persons resident outside India as accredited investors, and new PMS Regulations 2026 | Approved, not yet notified |
As set out in the NDI (Third Amendment) Rules 2026, RBI notification FEMA 395(4)/2026-RB, the Income-tax Rules 2026 and SEBI press release 59/2026.
The 13 June notification simplifies the old portfolio investment scheme. Its core stays: one designated account, run through a designated bank that reports the trades. Banks may still call it a PIS account.
The accredited-investor decision matters most for minimums. Accredited investors can agree a ticket below ₹50 lakh with the manager. Until SEBI notifies the change, the ₹50 lakh floor still applies to NRIs. Kalviro’s guide to the accredited investor in India will track it.
How PMS for NRIs is taxed: TDS on each sale
Every profitable sale in an NRI’s PMS triggers tax deducted at source. The rule sits in section 393(2) of the Income-tax Act 2025 (earlier section 195). Under the designated-bank route, the bank computes and deducts it; in other set-ups the deductor can differ.
For tax year 2026-27, gains on STT-paid listed shares held 12 months or less attract 20% (section 196). Gains on shares held longer attract 12.5% above ₹1.25 lakh a year (section 198). Surcharge applies at higher incomes, capped at 15% on these gains. A 4% cess comes on top. The top effective rates come to about 23.92% short-term and 14.95% long-term.
Two points catch NRIs out. The deductor takes tax sale by sale, so a manager who trades often pulls cash out of the account more often. And deductors usually ignore the ₹1.25 lakh long-term exemption. The NRI claims it in the tax return.
A worked example on ₹1 crore
Take an NRI with a ₹1 crore PMS on the NRE route and no other Indian income. No surcharge applies at this level. Over a year, the manager books ₹20 lakh of short-term gains and, separately, ₹20 lakh of long-term gains.
| Gain | TDS deducted | Final tax after return | Refund |
|---|---|---|---|
| ₹20 lakh short-term | ₹4.16 lakh (20% plus 4% cess) | ₹4.16 lakh | Nil |
| ₹20 lakh long-term | about ₹2.60 lakh (12.5% plus cess on the full gain) | ₹2.44 lakh (after the ₹1.25 lakh exemption) | about ₹0.16 lakh |
Illustrative. Kalviro calculation for tax year 2026-27. Actual TDS depends on the deductor’s method and total Indian income.
The NRI files an Indian return to claim the refund. Capital losses booked in the PMS can be set off against capital gains only through that return.
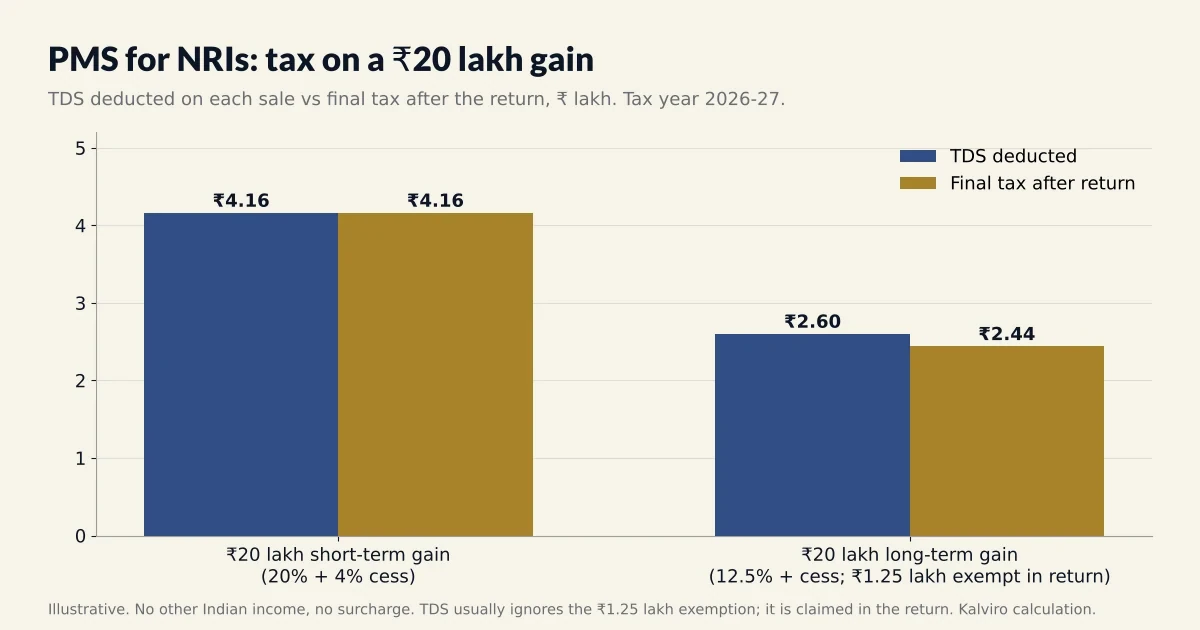
Treaty relief, the TRC and Form 41
A double tax avoidance agreement can lower Indian tax for a resident of the treaty country. To claim it, the NRI hands the deductor a tax residency certificate from the home country. A self-declaration in Form 41 (earlier Form 10F) goes with it.
The relief on share gains depends on each treaty’s capital gains article, so it varies by country. The home country may then tax the same gain under its own rules. It may or may not give credit for the Indian tax. A tax adviser in the country of residence should confirm the position before the account opens.
US and Canada residents: FATCA, PFIC and fewer managers
US-resident NRIs face two layers. FATCA requires Indian institutions to report US clients’ accounts. Many Indian managers therefore decline US clients or ask for extra documents. US tax rules also treat most foreign pooled funds as PFICs, which carry punitive tax and heavy reporting.
A PMS holds shares directly, and direct holdings of Indian operating companies are generally not PFICs. Cash the manager parks in liquid mutual funds or ETFs between trades can be. A US tax adviser should review the manager’s cash policy before the account opens. Canadian residents should run the same checks with the manager and a Canadian tax adviser.
Bringing the money home: limits and forms
On the repatriable route, sale proceeds reach the designated account after TDS. The investor can then send them abroad. On the non-repatriable route, money lands in NRO and can leave India only within the USD 1 million limit.
Each outward remittance from NRO needs an online declaration in Form 145. Where the rules require it, a chartered accountant also signs Form 146. These replaced Forms 15CA and 15CB for remittances from 1 April 2026.
Currency is the other part of the return. A PMS reports in rupees, so a fall in the rupee reduces what the NRI receives in dollars or dirhams. Kalviro’s note on currency risk for NRIs works through twenty years of that effect.
GIFT City PMS for NRIs: USD 75,000 and where the exemption stops
India’s International Financial Services Centre in GIFT City offers a dollar alternative. Under the IFSCA (Fund Management) Regulations 2025, an IFSC portfolio manager can take clients from USD 75,000. The earlier floor was USD 150,000. Money moves in and out in dollars, outside India’s rupee account system.
The tax position needs care. Schedule VI of the Income-tax Act 2025 exempts a non-resident’s IFSC portfolio income only where it arises outside India. A GIFT City PMS holding global shares can earn income free of Indian tax. One holding Indian shares still pays Indian tax on those gains. Kalviro’s notes on GIFT City PMS vs AIF and GIFT City tax myths set out the detail.
Onshore or GIFT City PMS for NRIs: two cases
| Point | NRI in Dubai | NRI in the US |
|---|---|---|
| Onshore PMS available | Subject to each manager’s country list | Fewer managers accept US clients |
| Home-country tax on gains | UAE levies no personal income tax | US taxes worldwide income; Indian tax handled through US foreign tax credit rules |
| Main Indian tax | TDS on each sale | TDS on each sale |
| PFIC concern | None | Direct shares generally outside PFIC; check cash in liquid funds |
| GIFT City PMS | USD 75,000, dollar account | USD 75,000; manager acceptance of US clients varies |
| Currency exposure | Rupee against dirham | Rupee against dollar |
Information as of October 2026. General description only; tax treatment depends on each investor’s facts.
For the Dubai investor, the choice mostly turns on minimum and currency. For the US investor, the first question is which managers will take the account. The second is how US tax treats the result.
What NRIs ask before opening a PMS account
Can NRIs invest in PMS in India? Yes. NRIs and OCIs can open a PMS account from ₹50 lakh through either route. The manager must accept their country of residence.
Is the minimum lower for NRIs? Not yet. On 24 September 2026 SEBI’s Board approved treating non-residents as accredited investors, which would allow lower tickets by agreement. The change applies only once notified.
Can I invest from my NRO account? Yes, on a non-repatriation basis. Money can then leave NRO only up to USD 1 million a financial year.
What does a PMS cost? A fixed fee, a performance fee or both, plus 18% GST. Operating expenses (capped at 0.5% a year) and brokerage come on top. Kalviro’s PMS fee calculator compares the options on your amount, and the SEBI PMS FAQs set out the rules.
Should a resident relative invest instead? That changes whose money it is and whose tax applies. For residents, Kalviro’s note on LRS vs NRI GIFT City covers the overseas routes.
PMS for NRIs works much as it does for residents, with three differences that decide the outcome. The account route sets how freely money comes home. Tax leaves the account with every profitable sale. And the country of residence sets which managers are open. Kalviro’s PMS strategies in India page lists the selective, curated strategies available.