

GIFT City PMS vs AIF for NRIs
A GIFT City PMS and a GIFT City AIF both let NRIs invest in US dollars through India’s international financial centre. The difference is what you own. In a PMS, a manager runs a portfolio of shares held in your name. In an AIF, you buy units of a pooled fund that many investors share.
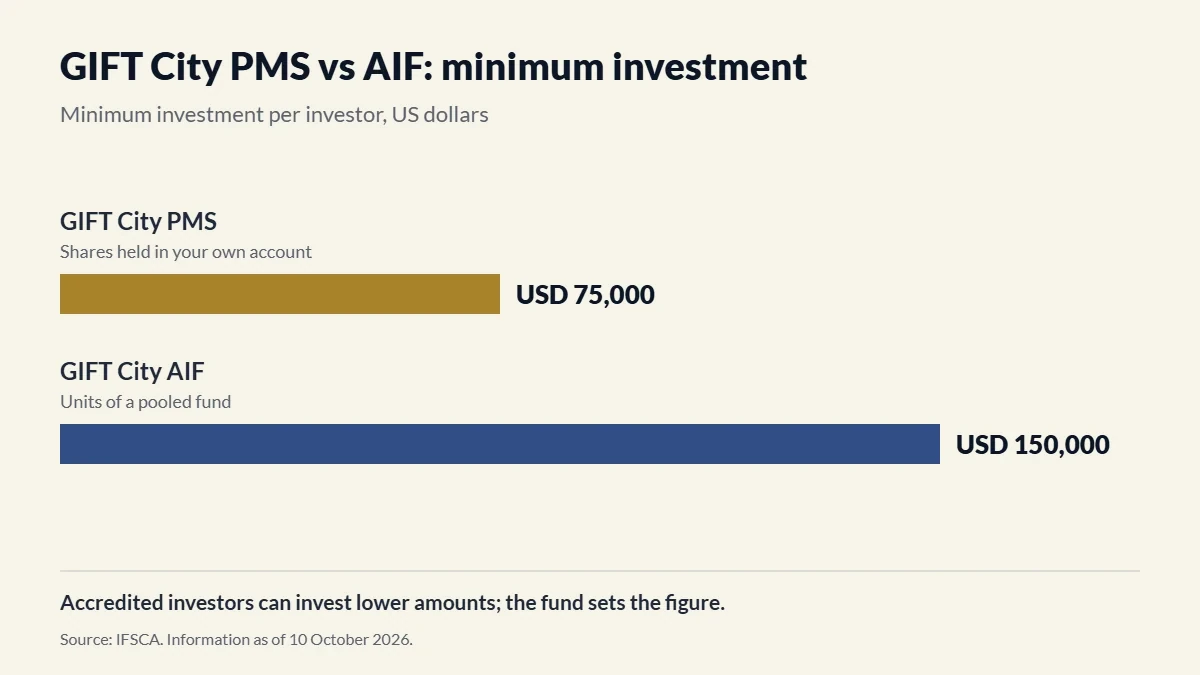
A GIFT City PMS starts at USD 75,000 and an AIF at USD 150,000. NRIs invest from a foreign account, and resident Indians can use the Liberalised Remittance Scheme.
The ownership difference also shapes what the manager can buy, how you exit and who pays the tax. Information is as of 10 October 2026.
GIFT City PMS vs AIF at a glance
| GIFT City PMS | GIFT City AIF | |
|---|---|---|
| What you own | Shares and securities in your own account | Units of a pooled fund |
| Minimum investment | USD 75,000 | USD 150,000 |
| Currency | US dollars, usually | US dollars, usually |
| What it can hold | Mainly listed shares and similar securities | Listed and unlisted shares, private equity, private credit, derivatives |
| Getting money out | Under the terms of your PMS agreement | Depends on the fund; many private funds lock money for years |
| Indian tax on Indian shares | Paid by you | Often paid by the fund |
| Regulator | IFSCA | IFSCA |
Information as of 10 October 2026. Source: IFSCA (Fund Management) Regulations 2025, as amended up to 10 September 2026; Income-tax Act 2025.
For a first-time investor, the choice is between owning shares directly from USD 75,000 or buying into a pooled fund from USD 150,000. You can usually close a PMS under its agreement, while many private AIFs hold money for several years. In both, the value of the investment can fall with markets and with the rupee-dollar rate.
How a GIFT City PMS works
You sign an agreement with a fund manager registered in GIFT City. The manager buys and sells for your account, and each holding is yours. Your statements show each holding, trade and fee. Before you sign, the manager gives you a disclosure document that sets out the strategy, fees and risks.
A GIFT City PMS can invest in India, abroad or both, so one strategy may hold Indian large caps and another US shares. Kalviro’s review of Phillip Capital Pioneer PMS shows what one GIFT City PMS holds and charges.
How a GIFT City AIF works
An AIF pools money from many investors under one offer document. You own units, and the fund owns the investments. GIFT City AIFs come in three broad types:
| Type | Typical strategy | Exit |
|---|---|---|
| Category I | Venture capital, start-ups, infrastructure | Fixed term |
| Category II | Private equity, private credit | Fixed term |
| Category III | Listed shares, long-short, derivatives | Open-ended or fixed term |
Information as of 10 October 2026. Source: IFSCA (Fund Management) Regulations 2025.
Many Category I and II funds draw your money in stages as they find investments. Kalviro’s note on AIF capital calls explains how that works.
Minimum investment for a GIFT City PMS and AIF
A GIFT City PMS starts at USD 75,000. A GIFT City AIF starts at USD 150,000. Onshore, a PMS needs ₹50 lakh and an AIF ₹1 crore. Accredited investors can invest lower amounts, and the fund sets the figure.
For smaller amounts, GIFT City also has mutual fund-style schemes and ETFs. Kalviro compares those in GIFT City mutual funds vs AIFs.
What each one can invest in
A GIFT City PMS that the manager runs on your behalf sticks mainly to listed shares, money market instruments and fund units. An AIF can go further, into unlisted companies, private credit, venture capital and derivatives.
So if the goal is private equity or private credit from GIFT City, an AIF is the route. If the goal is a portfolio of listed shares, both can do it, and the choice turns on ownership, minimum and tax.
Getting your money out
You can end a GIFT City PMS under the terms of your agreement. The manager sells the holdings or transfers them to you, subject to any exit fee in the disclosure document.
An AIF follows its offer document. A Category I or II fund usually returns money as it sells investments, often over several years. A Category III fund may let you redeem at set intervals, such as monthly or quarterly. Read the exit terms in the offer document before you invest.
How tax works in a GIFT City PMS vs AIF
In a GIFT City PMS, the shares are yours. Indian tax on gains from Indian shares falls on you, at the rates for non-residents. Gains on foreign shares held through a GIFT City PMS generally stay outside Indian tax.
Some GIFT City Category III funds are open only to non-residents. In those, the fund pays the Indian tax on Indian shares, and you generally have nothing further to pay in India on your units. Foreign shares inside such a fund are mostly outside Indian tax too. Category I and II funds pass most of their income through to investors, who pay the tax.
| Step | GIFT City PMS | Category III fund for non-residents |
|---|---|---|
| Long-term gain on Indian shares | USD 30,000 | USD 30,000 |
| Who pays Indian tax | You | The fund |
| Indian tax at 12.5% | About USD 3,750 | About USD 3,750 |
| Gain kept, for an NRI in the UAE | About USD 26,250 | About USD 26,250 |
Illustrative, as of 10 October 2026. Kalviro calculation under the Income-tax Act 2025. Ignores cess, the ₹1.25 lakh annual exemption, fees and currency moves.
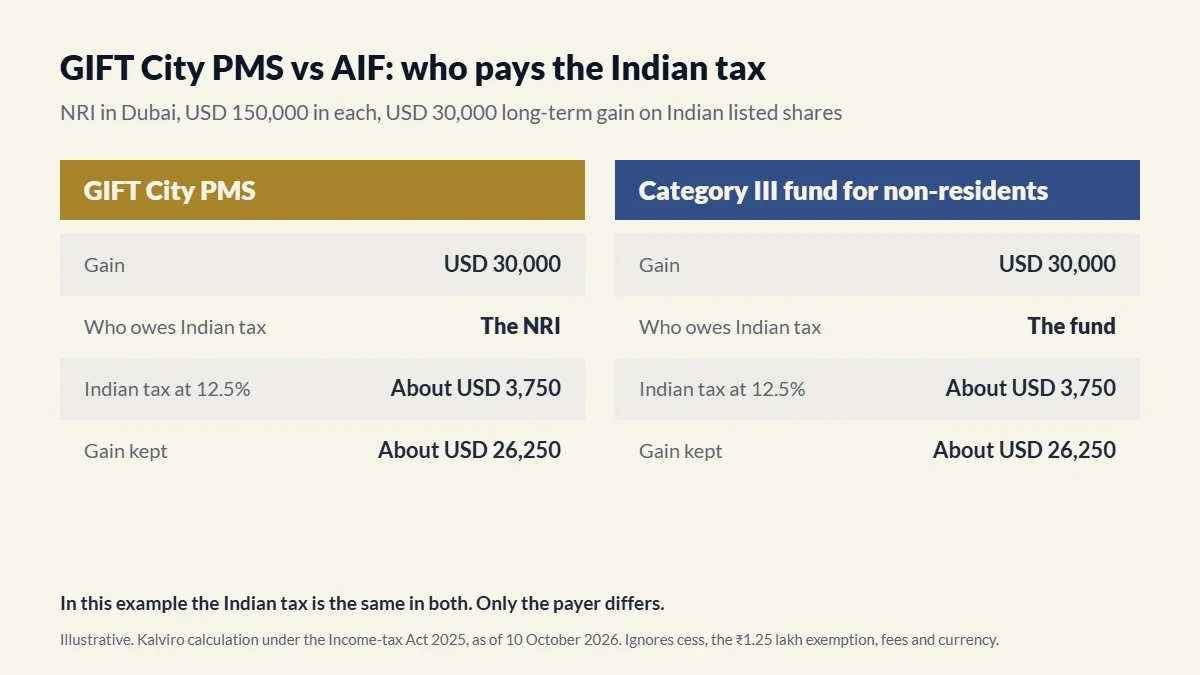
In this example the Indian tax is the same in both, and only the payer differs. Your country of residence may also tax the gain. If you live in the US or UK, ask a tax professional how your country treats fund units before you invest. Kalviro’s guide to GIFT City tax myths covers the wider picture.
Can residents invest?
Yes. Resident Indians can invest in a global (outbound) GIFT City PMS or AIF through the Liberalised Remittance Scheme, within USD 250,000 a year. India-focused (inbound) GIFT City funds are for NRIs only. The tax treatment differs from an NRI’s. Remittances above ₹10 lakh a year also attract 20% tax collected at source, which you can claim as a credit. Kalviro’s comparison of LRS and NRI routes into GIFT City covers the steps.
IFSCA reported 235 fund managers and 401 schemes in GIFT City at the end of June 2026.
Questions NRIs ask about GIFT City PMS and AIFs
Is a GIFT City PMS the same as an Indian PMS? No. It runs in US dollars, has a lower minimum in dollar terms and sits under IFSCA, not SEBI.
Can I switch from a GIFT City AIF to a GIFT City PMS? Not directly. You exit the fund on its terms and open a new PMS account.
Do I need to convert money into rupees? No. Both run in a foreign currency, usually US dollars. Your returns at home still move with the rupee and the dollar, as Kalviro’s note on currency risk for NRIs shows.
Does the GIFT City tax holiday cover my returns? No. The holiday applies to the fund manager’s own business income. Your tax depends on what the fund holds and where you live.
Can this guide tell me which one fits me? No. It explains how each works. Your residency, tax position and goals decide the fit, so read the offer documents and check the tax position with a professional.
What are the main risks? Market falls, currency moves and, in private AIFs, money locked for years. Fees also reduce returns, so compare the full fee schedule.
Two questions usually settle the choice between a GIFT City PMS and an AIF: whether you want the shares in your own name, and whether the strategy needs unlisted or private assets. Kalviro’s GIFT City PMS and funds page lists the PMS strategies and funds on offer, and the GIFT City investment for NRIs guide covers accounts and onboarding.
