

Currency Risk for NRIs: How INR Can Erase Equity Gains
Currency risk for NRIs is the chance that exchange-rate moves change what your India investment is worth in the currency you live on. That is usually USD, EUR, GBP, AED or SGD. The loss can happen even when the India-side return looks fine in rupees.
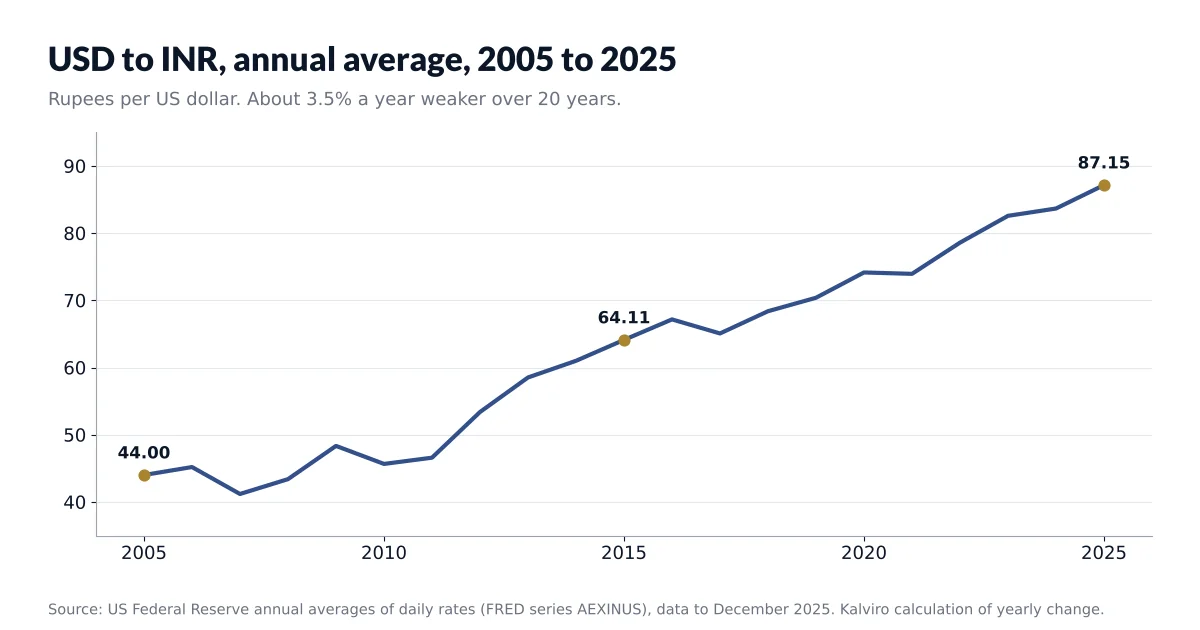
The record is long enough to measure. Federal Reserve data show the rupee averaging 44.00 to the US dollar in 2005 and 87.15 in 2025. Over those twenty years the rupee lost about 3.5% a year against the dollar. An NRI who earned 12% a year in rupees kept closer to 8–9% in dollars.
This page puts numbers on that gap. It covers the twenty-year record, a worked example, what gold shows, why the rupee drifts lower and what hedging costs. It also shows where GIFT City investments change the picture. Market data runs to December 2025, with 2026 developments noted where they matter.
The rupee against the dollar, 2005 to 2025
| Period | INR per USD (annual average) | Change in the rupee’s value |
|---|---|---|
| 2005 | 44.00 | Base year |
| 2015 | 64.11 | About 3.8% a year weaker from 2005 |
| 2025 | 87.15 | About 3.1% a year weaker from 2015 |
| 2005 to 2025 | 44.00 to 87.15 | About 3.5% a year weaker over 20 years |
Information as of December 2025. Annual averages of daily rates published by the US Federal Reserve (FRED series AEXINUS). Yearly rates of change are Kalviro calculations.
In practice, a rupee that buys a dollar’s worth of goods today has bought noticeably less each decade. If you spend in dollars, an India portfolio must first earn that loss back. Only then does it add to your wealth. The pace has not been steady: some years the rupee barely moved, and in others it fell sharply.
Currency risk for NRIs in one example: 3.5% a year on ₹1 crore
Take an NRI who moves ₹1 crore into Indian equities when the rate is 88 to the dollar. That is about USD 113,600.
Assume the portfolio earns 12% a year in rupees for ten years. It ends at about ₹3.11 crore. Now assume the rupee keeps its 2015–2025 pace and weakens about 3.1% a year, finishing near 120 to the dollar. The ₹3.11 crore converts back to roughly USD 259,600.
In rupees the money grew 3.1 times. In dollars it grew 2.3 times, which is about 8.6% a year instead of 12%. Fees and tax come off both numbers. The example is illustrative. Over any ten-year window the rupee could fall faster, fall slower or rise.
A useful rule of thumb is that the dollar return is roughly the rupee return minus the rupee’s fall. It loses accuracy over long periods or large moves. For your own dates, use the actual entry and exit rates. The RBI reference rate archive gives an official rate for each business day.
Gold shows how much of a rupee return is currency
Gold makes the currency effect easy to see. It trades in dollars worldwide, and its rupee price is simply the dollar price converted.
| Gold, annual average | 2005 | 2025 | Yearly change |
|---|---|---|---|
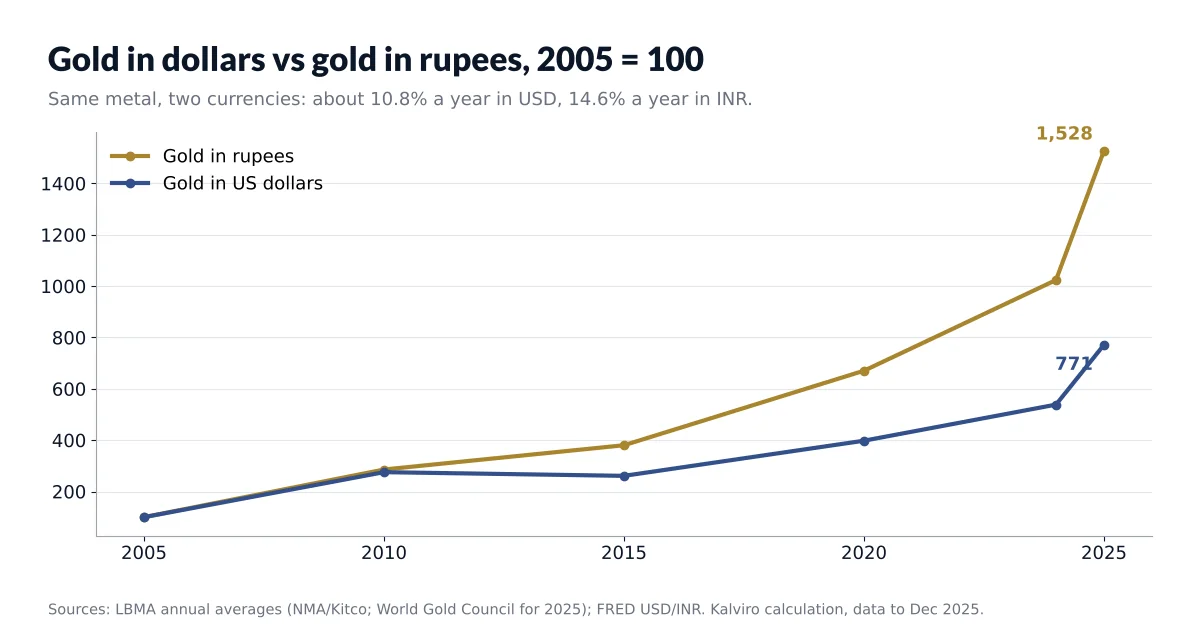
| In US dollars per ounce | USD 444.74 | USD 3,431 | About 10.8% |
| In rupees (dollar price × INR per USD) | ₹19,569 | ₹2,99,000 | About 14.6% |
Information as of December 2025. LBMA gold price annual averages: 2005 as compiled by NMA from Kitco; 2025 from the World Gold Council. Rupee figures use the FRED annual average exchange rates above. Kalviro calculations.
Over twenty years, the same ounce of gold returned about 14.6% a year in rupees. In dollars it returned about 10.8%. Close to four percentage points of the rupee return came from the rupee weakening, not from gold. The same arithmetic applies to any Indian asset. Part of a long-run rupee return is just the currency making up for its own fall.
Why the rupee drifts lower against the dollar
Four forces explain most of the long-run trend.
Inflation has usually run higher in India than in the US. Over time, a currency with higher inflation tends to buy less of a lower-inflation one.
India runs a current-account deficit. It imports most of its crude oil and much of the world’s gold. It pays for both in dollars. RBI balance-of-payments data put the deficit for 2025-26 at USD 25.2 billion, or 0.6% of GDP.
Portfolio money moves fast. When foreign investors sell Indian shares and bonds, they sell rupees too. These flows explain many of the sharp short-term falls.
A strong dollar pulls most emerging-market currencies down together. In those periods the rupee often falls with its peers, not on its own story.
The Reserve Bank of India smooths sharp moves by selling dollars from its reserves and through swap operations. Its stated aim is to contain volatility. It does not target a particular level, so the long-run drift continues.
2025 and 2026: the rupee’s latest fall
Business Standard reported that the rupee fell 4.74% against the dollar over 2025, its weakest year since 2022. It crossed 90 to the dollar in early December 2025 and briefly passed 91 later that month.
The fall continued into 2026. News reports put the rupee at record lows of about 95 to 97 per dollar in May and June 2026. RBI dollar sales and swaps then steadied it. None of this predicts the next move. It does show how one difficult year can overtake a five-year average.
Hedging currency risk for NRIs: what a forward costs
An NRI can lock in a future exchange rate with a currency forward through a bank. The price of that lock is the forward premium, which broadly reflects the gap between Indian and US interest rates.
Market reports put the one-year USD/INR forward premium at about 2.9% in early June 2026, after about 3.5% in mid-May. In early December 2025 it was about 2.65%. In plain terms, guaranteeing today’s exchange rate for one year cost about 2.9% of the amount hedged.
That number sits close to the rupee’s long-run pace of decline. A hedge therefore tends to swap an uncertain currency loss for a fairly certain cost of similar size. What it buys is predictability. That matters when the money has a known dollar use, such as a home purchase or school fees.
Most NRIs who hold Indian equities for many years leave them unhedged and accept the currency path. Rolling a hedge every year adds cost and paperwork. An equity portfolio also changes value daily, so no hedge fits it exactly.
Where GIFT City changes the currency path, and where it doesn’t
GIFT City funds take subscriptions and pay redemptions in foreign currency, usually US dollars. That removes some conversion steps. It does not remove the currency risk inside the fund if the fund holds rupee assets.
| Setup | What happens to currency risk |
|---|---|
| Onshore rupee equity, PMS or AIF | Full rupee exposure against your home currency |
| GIFT City fund in USD that holds Indian equities or rupee credit | You invest and redeem in USD, but the NAV still moves with the rupee |
| GIFT City fund in USD that holds global assets | Rupee exposure largely gone; market risk and any USD-to-home-currency risk remain |
| Foreign-currency deposit in a matching currency | Little currency risk against that currency; deposit-level returns |
A USD fund that buys Indian shares converts dollars into rupees first. The rupee’s fall then shows up in its dollar NAV. Kalviro’s guide to GIFT City investment for NRIs covers products and minimums. Residents investing through GIFT City use a different funding route, explained in LRS vs NRI GIFT City investing.
Currency risk for NRIs who spend euros, pounds or dirhams
The UAE dirham has been pegged to the US dollar at 3.6725 since 1997. For a Gulf-based NRI, the USD/INR record above is close to the AED/INR record.
For NRIs in Europe or the UK, the picture has two legs. A USD-denominated GIFT City fund still leaves a dollar-to-euro or dollar-to-pound move when the money is spent at home. An onshore rupee investment carries the rupee’s move against the euro or pound directly, which has its own history. Kalviro’s NRI global investing page covers non-rupee options for NRIs who want some assets outside the rupee entirely.
Sizing currency risk for NRIs against the currency you spend
One sentence helps before choosing any product: “My financial life is priced in ___.”
If the answer is dollars, measure every India holding in dollars. If it is euros or pounds, measure in those. NRIs who expect to retire in India face a smaller mismatch, because part of their future spending is in rupees.
Many NRIs hold India as a growth allocation beside home-currency assets. They size it so that a weak-rupee decade would not derail a mortgage or a child’s education abroad. The size usually gets revisited when the country of residence, the mortgage currency or the retirement plan changes. For listed equity through your own demat account, Kalviro’s note on PMS for NRIs covers the account set-up.
What NRIs ask about currency risk
Can anyone forecast USD/INR? Banks and research houses publish forecasts, and they often disagree. The long-run drift has been steady enough to plan around; the year-to-year path has not.
Does GIFT City remove currency risk for NRIs? Not when the fund holds Indian assets. It changes the funding and redemption currency. A GIFT City fund that holds global assets reduces rupee exposure. Separately, Kalviro’s note on GIFT City tax myths explains why tax treatment varies by scheme.
Should I hedge? A hedge suits money with a known foreign-currency use on a known date. For long-term equity, a hedge at about 2.9% a year (June 2026) costs close to what it protects against.
Do NRE or FCNR deposits avoid currency risk? An FCNR deposit stays in foreign currency, so its principal does not move with the rupee. An NRE deposit is in rupees and carries full currency risk, although its interest is tax-free in India while the holder is non-resident under FEMA.
Does a strong rupee year help? Yes. Currency risk for NRIs works both ways. When the rupee rises, a dollar-based investor earns more than the rupee return.
Currency risk for NRIs is the gap between a rupee return and its value in the currency you spend. From 2005 to 2025 that gap averaged about 3.5% a year against the dollar, with sharp falls in single years such as 2025. A hedge fixes the rate for a similar cost, and a USD wrapper changes the route without changing what the fund owns. The decisions that matter are how much to hold in rupees and which currency to measure it in.
