

Accredited Investor in India: Eligibility Criteria 2026
An accredited investor in India is a person or entity that a SEBI-recognised agency has certified against set income or net-worth tests. The status removes some minimum-investment floors in AIFs and PMS. In return, the investor accepts fewer regulatory guardrails.
SEBI’s Board approved a wider framework on 24 September 2026 (press release PR No. 59/2026). It adds a ₹5 crore securities-market test, automatic status for non-residents and new routes for LLPs, and lets fund managers accredit investors with a single three-year validity. These changes apply only once SEBI notifies the amended rules and issues its circular. Until then, the current tests and the agency route apply.
This page covers the current and approved tests, how to apply through CVL or NDML, the documents, fees and validity, and what the status changes for PMS and AIF minimums. Information is as of 17 October 2026.
In this article10 sections
Accredited investor India rules at a glance (October 2026)
| Point | Current rules | Approved by SEBI’s Board on 24 September 2026, pending notification |
|---|---|---|
| Who certifies | An accreditation agency: CVL or NDML | Also AIF managers and portfolio managers |
| Individuals, HUFs, family trusts, sole proprietors | Income, net-worth or combined test | Adds a test of ₹5 crore of securities-market exposure |
| Companies and trusts other than family trusts | ₹50 crore net worth | Adds a test of ₹20 crore of securities-market exposure |
| LLPs | Not listed separately | ₹50 crore net worth, ₹20 crore of securities-market exposure, or every partner accredited |
| Partnership firms | Every partner accredited | No change |
| Persons resident outside India, including NRIs and OCIs living abroad | Same tests and certificate as residents | Accredited automatically, with no certificate |
| Validity | Agency certificate: two or three years, set by the years of records submitted | Three years for both the agency and manager routes |
Information as of 17 October 2026. Sources: SEBI circulars of 18 December 2023 and 9 January 2026; SEBI Board memorandum and press release (PR No. 59/2026) for the meeting of 24 September 2026.
Accreditation lets an investor go below the usual ₹50 lakh PMS or ₹1 crore AIF floor where a fund allows it. It also opens a few products reserved for accredited investors. You prove income or wealth to an agency, pay a fee and hold the status for two or three years. Fewer protections come with it, and the products stay as risky and illiquid as before.
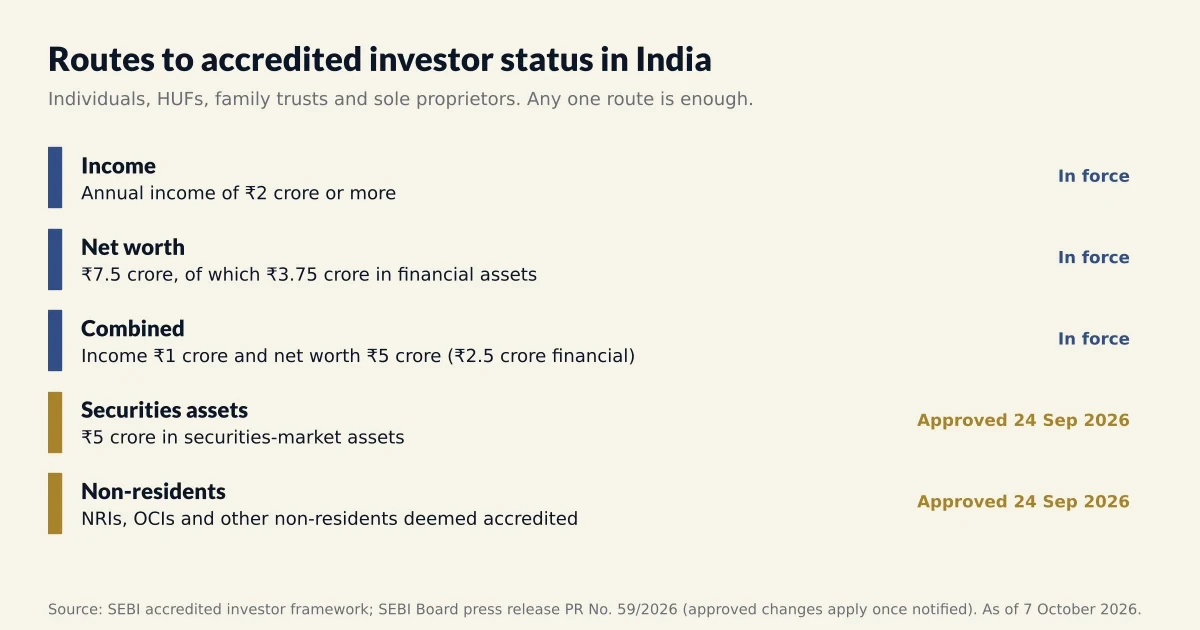
Four ways to qualify as an accredited investor in India
Individuals, Hindu undivided families, family trusts and sole proprietorships can qualify through any one of three tests today. SEBI’s Board has approved a fourth, which applies once SEBI notifies it.
| Route | Test | Proof the agency asks for |
|---|---|---|
| Income | Annual income of ₹2 crore or more | Income-tax return or ITR acknowledgement |
| Net worth | ₹7.5 crore or more, with at least ₹3.75 crore in financial assets | Chartered accountant’s net-worth certificate, no older than six months |
| Combined | Income of ₹1 crore or more and net worth of ₹5 crore or more, with at least ₹2.5 crore in financial assets | ITR plus a CA net-worth certificate |
| Securities-market exposure (approved, pending notification) | ₹5 crore or more in securities-market holdings | eCAS or broker statement no older than six months, or a CA certificate (as approved; SEBI’s circular will confirm) |
Information as of 17 October 2026. Sources: SEBI circular of 9 January 2026 (documents); SEBI Board memorandum for the meeting of 24 September 2026 (securities-market route).
For individuals, the primary residence does not count towards net worth. For the new route, SEBI’s Board memorandum proposed counting demat shares and bonds, REIT, InvIT and AIF units, mutual fund folios, futures at notional value and overseas market investments. Fixed deposits count under the net-worth test but not here. SEBI estimated that about 3.7 lakh investors could qualify through this route alone, against roughly 96,000 AIF investors today.
Governments and their agencies, qualified institutional buyers and multilateral agencies hold the status automatically. SEBI’s Board has approved adding every person resident outside India to that list, pending notification. An Indian family office does not; it qualifies through the entity tests.
How to get an accredited investor certificate in India: CVL and NDML
SEBI names two accreditation agencies in its Board memorandum on the framework. The “CVL” in “CVL accredited investor” refers to CDSL Ventures Limited, a wholly owned CDSL subsidiary. The other agency is NSDL Database Management Limited (NDML). A certificate from either works with any AIF or PMS manager.
Step by step: applying through an agency
1. Pick the test you meet and count the years. One year of qualifying records gives a two-year certificate; two years give three.
2. Gather the documents in the table below. For the net-worth route, ask for a CA certificate dated within the last six months.
3. Register on the agency’s portal: aia.cvlindia.com for CVL, or aa.ndml.in for NDML. CVL lists four stages: registration, details, document upload and payment.
4. Pay the fees, then share the certificate with the fund manager. Both agencies let managers verify a certificate.
CVL says it issues the certificate within three business days when the documents are in order. Its portal showed an average of one working day (T+1) on 16 October 2026. NDML does not publish a turnaround. Meanwhile, an AIF manager may sign the contribution agreement, but it may not take money until the certificate arrives.
Documents the agencies ask for
| What you show | Individual, HUF or sole proprietor | Company, LLP or trust |
|---|---|---|
| Identity and address | PAN and an officially valid document, such as a passport or Aadhaar | PAN plus the incorporation document or registered trust deed |
| Authority to apply | Not needed | Letter from the authorised signatory |
| Income or net worth | ITR or ITR acknowledgement for each year relied on, or a CA net-worth certificate | Audited financial statements, or a CA net-worth certificate |
| Declaration | Signed statement that the submissions are true | Same |
Information as of 17 October 2026. Source: SEBI circular of 9 January 2026, Annexure A.
SEBI’s January 2026 circular dropped the detailed net-worth break-up, so the accountant may simply confirm that the investor clears the threshold. The agency can still ask for more if anything looks inconsistent.
Fees and turnaround at CVL and NDML
| CVL (CDSL Ventures) | NDML (NSDL Database Management) | |
|---|---|---|
| Processing fee, individuals | ₹5,000 | ₹5,000 |
| Certificate fee, two years | ₹5,000 | ₹5,000 |
| Certificate fee, three years | ₹9,500 | ₹9,500 |
| Total for an individual | ₹10,000 (two years) or ₹14,500 (three years); the tariff does not mention GST | ₹11,800 (two years) or ₹17,110 (three years), with 18% GST |
| Stated turnaround | Within 3 business days; average T+1 working day on 16 October 2026 | Not published |
| Certificates issued | 2,841 issued and 2,773 valid on 16 October 2026 | Not published |
Information as of 17 October 2026. Sources: CVL accreditation agency page and CVL-AIA portal; NDML accreditation agency fee calculator.
Take an individual with two years of ITRs above ₹2 crore. A three-year accredited investor certificate in India then costs ₹14,500 at CVL before any GST, or ₹17,110 at NDML with GST. That works out to roughly ₹4,800 to ₹5,700 a year. Companies, LLPs and non-family trusts pay more: ₹28,500 plus processing for three years at CVL.
How long accredited investor status in India lasts
Under the agency route, SEBI’s circular of 18 December 2023 sets two terms. A certificate lasts two years when the investor met the test in the preceding financial year. It lasts three years when they met it in each of the two preceding years. Renewal needs fresh documents.
SEBI’s Board has approved a single three-year term for both routes, based on the latest financial data. It takes effect once SEBI issues its circular.
Status also sticks to the investment. An investor accredited into a scheme stays accredited for that scheme’s life, even if their income or net worth later falls. A new commitment needs a valid status at the time. Those with automatic status need no certificate and no renewal; non-residents join them once SEBI notifies the change.
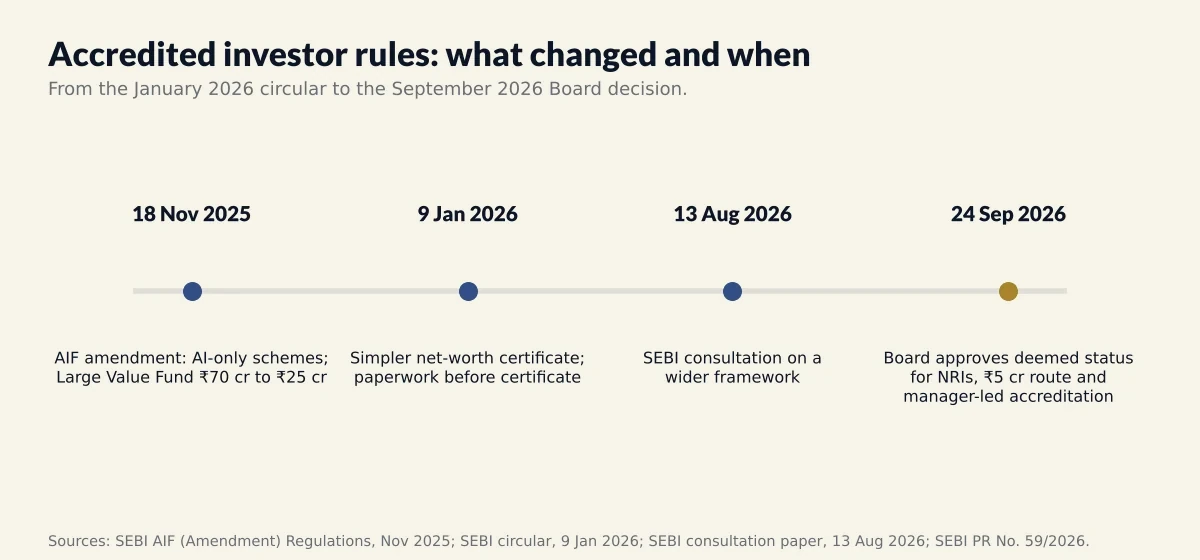
What accreditation changes for PMS and AIF minimums
| Product | Usual minimum or rule | For accredited investors |
|---|---|---|
| AIF | ₹1 crore commitment | No minimum ticket where the scheme allows |
| PMS | ₹50 lakh | No minimum where the strategy allows |
| Special situation fund | ₹10 crore | ₹5 crore |
| AIF Large Value Fund | Not open to others | ₹25 crore per investor (cut from ₹70 crore in November 2025) |
| Accredited-investors-only AIF scheme | Not open to others | Open; investors do not count towards the 1,000-investor cap |
| Angel funds and co-investment vehicles | Not open to others | Open to accredited investors only |
| GIFT City AIF (IFSCA rules) | USD 150,000 | USD 50,000 |
Information as of 17 October 2026. Sources: SEBI Board memorandum for the meeting of 24 September 2026; SEBI AIF (Amendment) Regulations, 18 November 2025; SEBI consultation paper, 13 August 2026; IFSCA-regulated fund minimums for GIFT City.
The table shows access, not suitability. A lower ticket lets an investor size a position smaller, which can help spread money across managers. It also makes it easier to put a large share of wealth into illiquid products. Each manager still sets its own minimum, and many keep ₹1 crore or more.
SEBI’s new Portfolio Managers Regulations, 2026 apply from 1 April 2027. They keep the ₹50 lakh PMS minimum and keep the exemption for accredited investors. Kalviro’s note on the ₹50 lakh PMS minimum covers what that ticket buys.
NRIs and OCIs: automatic accredited investor status approved
For NRIs this is the largest change. Today an NRI who wants accredited terms must clear the resident tests and get a certificate. SEBI’s Board has approved treating every person resident outside India, as FEMA defines it, as an accredited investor in India without a certificate. The change applies once SEBI notifies the amended rules.
A non-resident would then no longer face the ₹1 crore AIF or ₹50 lakh PMS floor by default. The scheme would still have to allow a smaller ticket, and many managers keep their own minimums. Until SEBI notifies the change, the current tests and certificate apply.
Repatriation rules, tax and KYC stay the same. US and Canadian residents still need a fund that accepts them. Kalviro’s page on PMS for NRIs compares the onshore and GIFT City routes.
Manager-led accreditation: approved, waiting for SEBI’s circular
The Board also approved a second route. AIF managers and portfolio managers may assess an investor’s status during onboarding, using the same kinds of documents. The assessment would last three years across the AIF and PMS products of one group. An unrelated manager would assess the investor again. SEBI’s safeguards include a written accreditation policy kept apart from sales, audit, and action against a manager who accredits carelessly.
SEBI kept the agency route for investors who use several unrelated managers, or who prefer not to share financial documents with a fund house. Managers need SEBI’s circular before they can use the new route, and SEBI’s circulars page listed none on 17 October 2026.
What an accredited investor gives up
Accreditation trades protection for flexibility, and the investor signs consent to that trade. Large Value Funds can run with relaxed norms on tenure extensions and concentration. In PMS, a large value accredited investor can let the manager put up to 100% of the portfolio in unlisted securities, against 25% for other non-discretionary clients.
None of this lowers the manager’s duty to disclose, but it shifts more of the judgement to the investor. The PPM or PMS disclosure document deserves a full read: the fee base, the term and extensions, the valuation method and the timing of payouts.
Where the accredited investor rules sit
| Rule | Where SEBI sets it |
|---|---|
| Definition, tests and automatic status | AIF Regulations 2012, regulation 2(1)(ab); changes approved by SEBI’s Board on 24 September 2026 (PR No. 59/2026), pending notification |
| Agency process and documents | SEBI master circular for AIFs, chapter on accredited investors; circular HO/19/34/11(9)2025-AFD-POD1/I/2286/2026 (9 January 2026) |
| Two- and three-year validity | Circular SEBI/HO/AFD/PoD1/CIR/2023/189 (18 December 2023) |
| Manager-led route and a common three-year validity | SEBI Board decision of 24 September 2026; circular awaited |
| PMS rules | The PMS Regulations use the AIF definition |
Information as of 17 October 2026.
Accredited investor questions from investors in India
Is my CVL KRA KYC the same as being an accredited investor in India? No. CVL runs a KYC registration agency and, separately, the accreditation portal. KYC alone does not make anyone accredited; accreditation needs its own application on the CVL-AIA portal.
How many accredited investors are there? SEBI’s Board memorandum counted 4,492 on 28 August 2026, up from 649 on 29 May 2025. They held AIF units worth about ₹2.31 lakh crore at par on 31 July 2026, nearly 33% of all AIF investments.
Does accreditation make sense for a ₹50 lakh ticket? Only where the fund or strategy offers that ticket size. Check the scheme’s minimum before paying ₹10,000 or more for a certificate.
Can a wholly owned subsidiary use its parent’s net worth? No. SEBI did not adopt that proposal, so the subsidiary has to clear the company test on its own.
Does accreditation change tax? No. Tax follows the product, whether an AIF category or a PMS account.
Does every AIF require accreditation? No. Most AIFs accept other investors at the ₹1 crore minimum. Accreditation matters for lower tickets, Large Value Funds, angel funds and accredited-only schemes. Kalviro’s AIFs in India page lists the structures available.
The accredited investor framework in India is moving from a certificate held by a few thousand people to a status that could cover lakhs. It changes what an investor may buy and at what size. The risk in the product stays the same, and the fund’s own documents still set the commitment, the lock-in and when the money comes back.