

FOMO Investing: What Chasing Returns Costs Indian Investors
FOMO investing means buying because others are making money, not because the investment fits a plan. In India it shows up as a rush into a hot theme, a stock tip from a friend or a PMS that topped last year’s tables. The money usually arrives after the best returns are already in the price.
Detailed data now exists on what this costs. SEBI’s own studies track losses in futures and options. Fund scorecards track how often last year’s winners stay ahead. This guide sets out that evidence, then a seven-step check for anyone choosing a portfolio manager. Figures are as of October 2026.
What FOMO investing looks like in Indian markets
Fear of missing out turns a price rise into a reason to buy. The trigger is social: a WhatsApp group, a rank list, a relative’s gains or a “closing soon” line from a seller. The decision skips the questions an investor would normally ask about risk, cost and fit.
Three patterns recur. Retail traders crowd into futures and options after a strong run. Mutual fund money floods into the theme of the moment, often through new fund offers. And investors choose a PMS or fund on its last twelve months alone.
Each pattern buys after a rise. Each also tends to sell after a fall, which locks in the loss.
The F&O evidence: SEBI’s own numbers
SEBI’s study of 23 September 2024 covered individual traders in equity futures and options from FY22 to FY24. It found that 93% of more than one crore traders lost money over the three years. Their combined losses came to about ₹1.8 lakh crore, or roughly ₹2 lakh per trader.
SEBI’s latest study, published in August 2026, covers FY25 and FY26. In FY26, 87.7% of individual traders lost money, down from 90.9% in FY25. Their net losses came to ₹91,685 crore in FY26, against a revised ₹1,11,788 crore the year before. Short-term trading driven by excitement now has a measured record, and it is poor.
Thematic fund rushes and the timing gap
FOMO investing shows up in mutual fund flows too. AMFI’s monthly note for June 2024 shows sectoral and thematic funds took ₹22,351 crore of net inflows. Nine new fund offers in the category raised ₹12,974 crore of it, more than half.
The pattern is familiar. A theme does well for two or three years. Fund houses launch products to meet the demand. Investors buy near the top, and many sell after the next fall. The fund’s reported return may stay healthy while the average investor’s return lags it.
The gap between a fund’s return and its investors’ return comes from timing: money arriving after the rise and leaving after the fall. No regulator publishes this gap for Indian funds, so an investor can only check it on their own statements, by comparing their XIRR with the fund’s return over the same period.
Why last year’s winners rarely stay on top
S&P Dow Jones Indices publishes the SPIVA India Scorecard, which compares active funds with their benchmarks. In calendar 2025, only 12.1% of Indian mid and small-cap funds lagged their benchmark. Over ten years, 79.0% did.
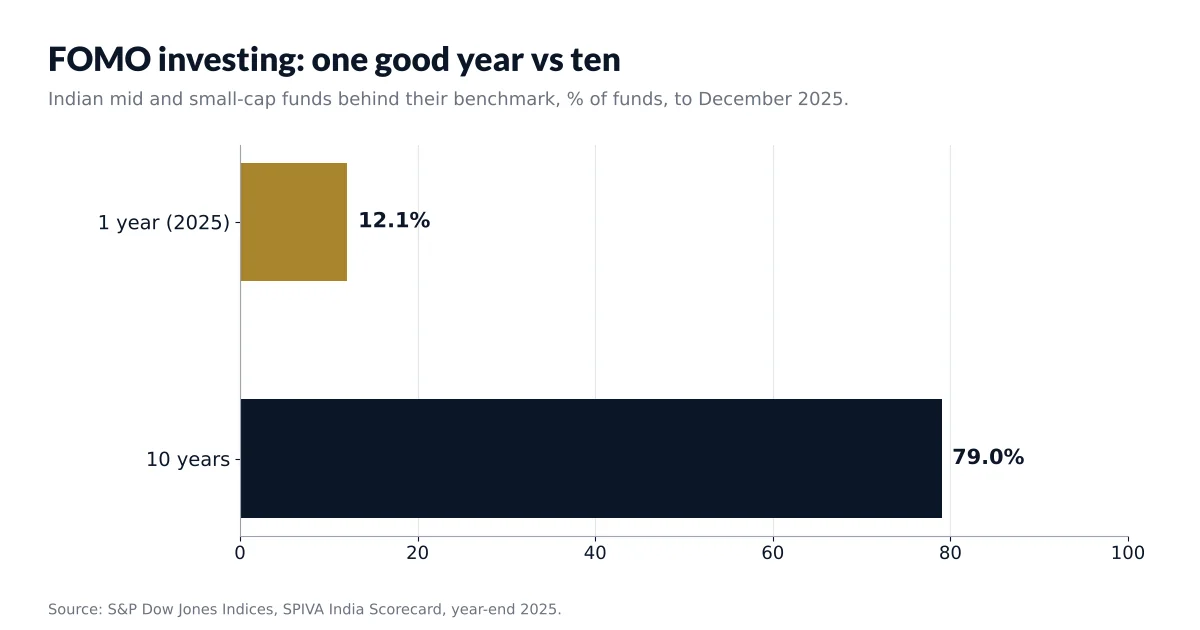
One strong year says little about the next ten. A manager can top a table because of one sector bet, one size bias or one lucky stock. FOMO investing treats that year as proof of skill.
PMS data point the same way. A Cafemutual analysis of APMI data as of May 2026 found that 57.6% of 543 discretionary equity PMS strategies beat their benchmark over five years. The rest, more than four in ten, did not. Benchmarks also differ between managers, which makes headline rankings harder to compare. Kalviro’s note on PMS performance metrics explains how to read a return against the right index.
The arithmetic of a late entry
Buying after a rally raises the risk of buying near a peak. The cost of a fall is larger than it looks, because a loss needs a bigger gain to recover.
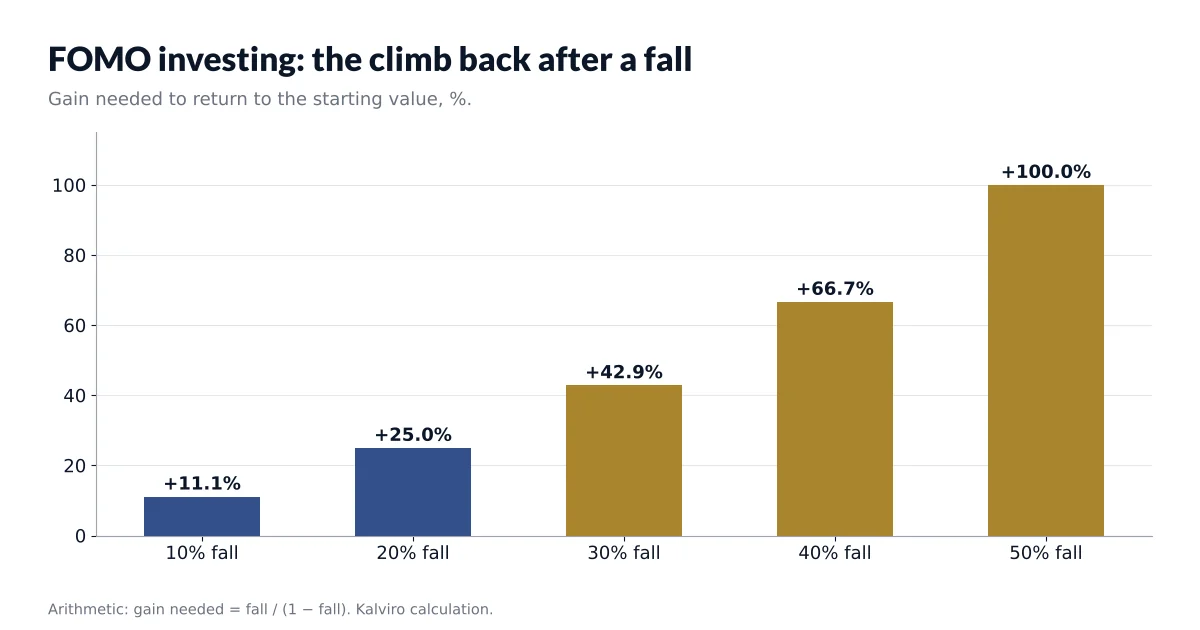
| Fall from the peak | Gain needed to get back |
|---|---|
| 10% | 11.1% |
| 20% | 25.0% |
| 30% | 42.9% |
| 40% | 66.7% |
| 50% | 100.0% |
Take ₹50 lakh placed in a concentrated PMS at a peak. A 30% fall takes it to ₹35 lakh. At 12% a year, the account needs a little over three years just to reach ₹50 lakh again. A fixed fee charged through those years makes the climb longer.
Seven checks before FOMO investing in a PMS
A written check slows the decision down. It works best if you finish it before you look at the return table.
- Write down the job of this money. Long-term growth, a satellite idea next to mutual funds, or a specific theme? If you can’t say, wait.
- Ask how the manager finds, sizes and sells ideas. A clear answer names the filters, the position limits and the sell rules. Ask what would make the manager exit a favourite stock.
- Study the worst periods. Ask for the deepest fall and how long recovery took. Compare that with how long you could hold through a fall without selling.
- Count concentration and turnover. Fifteen stocks behave differently from forty. High turnover raises brokerage and short-term tax, since the shares sit in your own demat account.
- Price the fee in rupees. A fixed fee, a performance fee above a hurdle, or both: run your amount through the PMS fee calculator under a flat, a steady and a strong return path.
- Look past the best year. Compare returns against the strategy’s own benchmark over three and five years, and across a rising and a falling market.
- Check liquidity and size. A PMS has no lock-in, but an exit load of up to 3% can apply in year one. Size the account so a deep fall would not force a sale. Kalviro’s ₹50 lakh PMS guide works through a first account at the minimum.
A fuller list sits in Kalviro’s guide to PMS selection criteria. The point of the seven checks is order: the return comes last.
Sales lines that signal FOMO investing
Some phrases push a decision faster than the facts allow. “Number one over twelve months” invites a one-year comparison. “Slots are closing” adds a deadline that rarely exists for an open PMS strategy. “Everyone is putting money here” replaces your plan with someone else’s.
Each line has a useful reply. Ask for the three- and five-year record against the benchmark, the deepest fall, the fee on your amount, and the conditions in which the strategy has lagged. A manager with a clear process will have answers ready.
FOMO investing: questions investors ask
Is it ever right to buy after a strong run? Yes, if the investment passes the same checks it would face after a weak year. The run itself is not a reason to buy or to avoid it.
How do I stop FOMO when friends are making money? Write your plan and the seven checks before you hear the next tip. If a step is incomplete, don’t fund it, whoever else already has.
Does a top-ranked PMS stay at the top? No study tracks this for Indian PMS. For mutual funds, the SPIVA figures show that one good year says little about ten. Judge a manager over several years against its own benchmark.
Is a falling market a reason to sell a PMS? Not by itself. Check whether the manager is following the stated process. A fall within the range the strategy has shown before is part of owning it.
What does FOMO investing cost? SEBI found 93% of individual F&O traders lost money over FY22 to FY24, and 87.7% lost money in FY26. In funds, the cost shows up as investors earning less than the funds they own, because they buy high and sell low.
FOMO investing feels like urgency and costs like a tax on timing. The evidence from SEBI, AMFI and the SPIVA scorecard points the same way: buying what has just done well, and selling what has just fallen, hands returns to someone else. A written check, run before the return table, is the simplest defence.
